The Public Record
Read the source documents
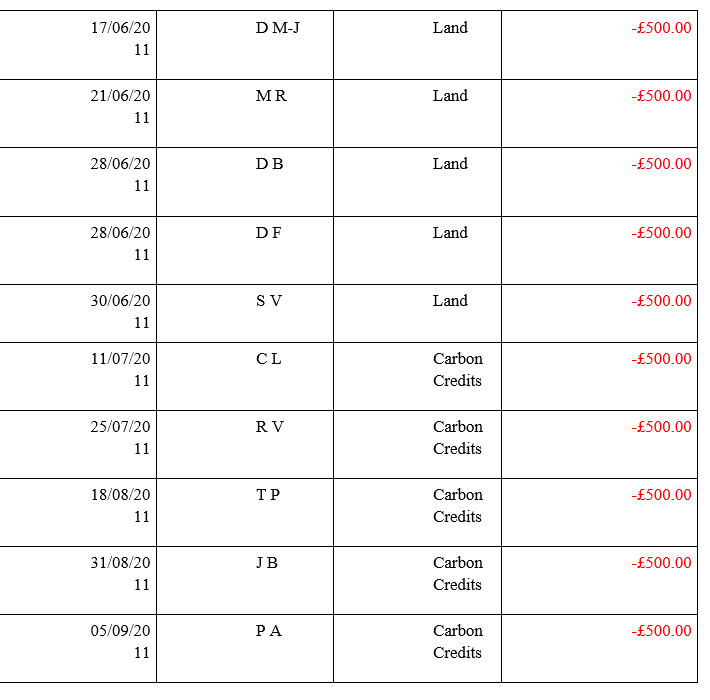
Refund schedule, part 1
A reproduced schedule with dates, customer initials and amounts. It is not a bank statement.
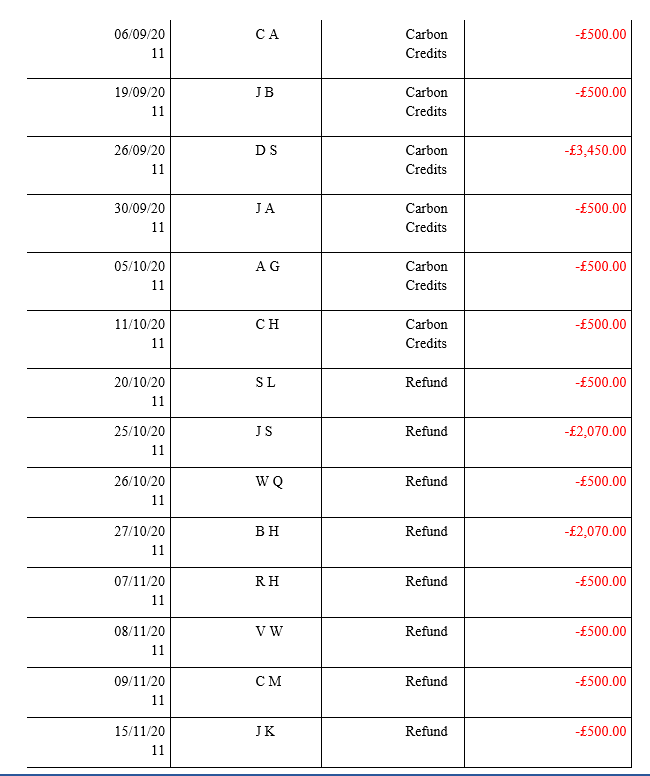
Refund schedule, part 3
Final reproduced schedule extract. Listed totals should not be treated as independently reconciled bank payments.
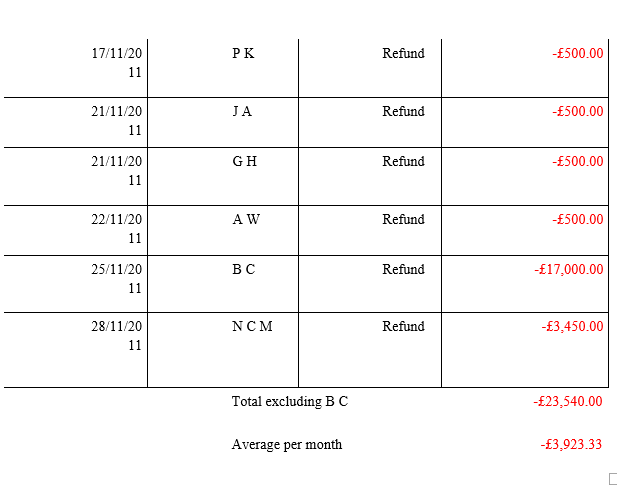
Tullett Brown offered a no-quibble refund policy. You can see below a list of the refunds made.
There had been instances where clients changed their minds and in each case, the client was reimbursed without quibble or question.
Our sales process required each client to pay a £500 deposit over the telephone (via credit or debit card). If the client then changed their mind over the next few days and asked for a refund, this would be given with no questions asked. In the six-month window from 17/06/11 to 28/11/11, the company refunded at least thirty deposits totalling £23,540 as follows.
I have abbreviated the clients’ names to initials for obvious reasons
Refunds After Completion
During this same time window, the company refunded four clients in full after they had fully completed the transaction. These were FULL REFUNDS AFTER COMPLETION – something that is unheard of:
25/10/2011 J S £2070.00 Carbon Credits
27/10/2011 B H £2070.00 Carbon Credits
26/09/2011 D S £3450.00 Carbon Credits
28/11/2011 N C M £3450.00 Carbon Credits
Is this behaviour consistent with a scam company? What would be the point of defrauding your customer only to refund them when asked?
Terms of Business
Tullett Brown required all prospective clients to read and sign our Terms of Business before engaging in any sales aspect. We could introduce ourselves and explain who we were and what we did, BUT could not engage in any sales activity until our Terms of Business had been signed by the prospect. This is an extremely high standard compared to other non-regulated brokers.
Tullett Brown was not required to do this but wanted to ensure that our clients understood the risks and were fully aware of the nature of these products. This is yet another example of Tullett Brown going above and beyond what was necessary at the time to ensure full client understanding.
See full Terms Of Business here
In it is contained the following risk warning:
RISK WARNING
● All investments are speculative and will fluctuate in value. It should not be assumed that the value of investments would always rise. Past performance is not a reliable indicator of future results. You may get back less than the amount originally invested or even lose the full amount.
● You should carefully consider in the light of your financial resources whether investing in carbon credits is suitable for you.
● Changes in currency exchange rates may adversely affect the value of any overseas investments or investments denominated in a foreign currency.
● There may be a big difference between the buying price and the selling price of carbon credits. If you have to sell them immediately, you may get back much less than you paid for them. You may have difficulty in selling carbon credits at the price you wish to achieve and, in some circumstances, it may be difficult to sell them at any price. It can be difficult to assess what would be a proper market price for these investments. You should not invest in carbon credits unless you have thought carefully about whether you can afford to do so and have taken appropriate independent advice.
● Representations made by our sales consultants, agents or sales literature either orally, on paper or in electronic form do not form part of these terms. We give no warranty as to the future value of carbon credits.
● Forwards, options and other derivative contracts concerning carbon credits are regulated investments in the United Kingdom. However, carbon credits sold by us are not derivatives and, as such, are not regulated investments. Accordingly, we are not required to be regulated by the Financial Services Authority (" FSA") or any other regulator in the United Kingdom. This means, among other things, that a person buying carbon credits from us will not benefit from any protections afforded by the FSA and would not have access to the Financial Services Ombudsman or the Financial Services Compensation Scheme.
See original here
By law, Tullett Brown was not required to have any Terms of Business. So let me ask you - is this the kind of behaviour that you would expect from a scam operation?
Compliance Department
Tullett Brown had a compliance team consisting of three people to ensure that sales were done responsibly and the risks were fully explained.
Compliance Calls
At Tullett Brown, all calls were recorded for training and monitoring purposes.
When a sale was made. Our broker was REQUIRED to read out the risks associated with the investment. As a second layer, just to be sure, the compliance team would call the investor the following day and ask if the risks had been explained to the investor. Had any investor said no or was unsure, the compliance officer would then read the risks to the investor again before asking if the investor would still like to continue with the investment.
This Tullett Brown employee was a junior compliance officer conducting a compliance call.
LISTEN TO THE COMPLIANCE CALL HERE.
How many scam companies have such measures in place? Is this consistent with a scam company? In fact, why would any scam company record their calls?